Mill Floor Millions: Why US Timber Producers Are Leaving Residue Revenue Behind
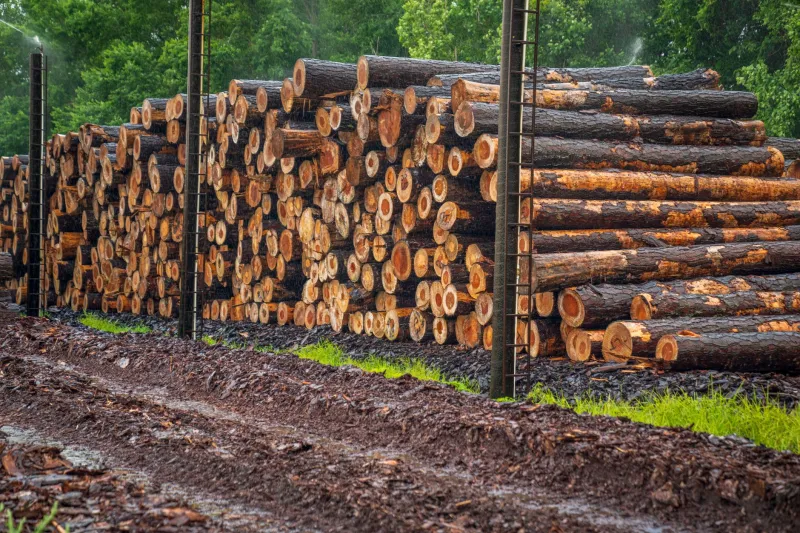
Every operating day, a mid-size timber mill in the American South or Pacific Northwest generates tons of material that never becomes a board, a beam, or a panel. Sawdust accumulates in collection bins. Bark piles grow at the yard perimeter. Low-grade fiber—too knotted or narrow for dimensional lumber—gets routed to the chipper or, in some cases, simply disposed of at cost. For decades, this was an accepted reality of the processing floor. Today, it represents a measurable revenue gap that forward-looking enterprises can no longer afford to ignore.
Conservative industry estimates suggest that residue monetization, when pursued systematically, can recover between 5 and 15 percent of potential processing revenue. For a mill generating $40 million annually, that range translates to $2 million to $6 million in value that currently walks out the door as waste. The gap persists not because buyers are absent—they are not—but because the market intelligence, logistics infrastructure, and cross-functional coordination required to close it remain underdeveloped at most US operations.
The Buyer Landscape Has Quietly Matured
The market for wood residues has undergone a significant structural shift over the past decade, driven by intersecting pressures in energy policy, biochemical innovation, and industrial decarbonization. Three buyer categories now represent genuine, scalable demand for mill-generated residue streams.
Wood pellet producers represent the most established channel. The US is the world's largest exporter of industrial wood pellets, with facilities concentrated in the Southeast shipping primarily to European utility operators under long-term offtake agreements. These producers require consistent fiber supply—typically clean sawdust and dry shavings—and are actively seeking regional sourcing relationships to reduce their own input costs. For mills located within economical trucking distance of pellet facilities in states such as Georgia, Alabama, and Virginia, this channel offers relatively predictable pricing and volume commitments.
Biochemical and bioproduct firms represent a higher-value but more complex opportunity. Companies developing bio-based chemicals, lignin derivatives, and cellulosic ethanol intermediates are increasingly sourcing from timber residues rather than agricultural feedstocks. Bark fractions, in particular, contain extractives with commercial value in adhesives, resins, and specialty chemicals. This buyer segment tends to require tighter specification tolerances and may demand exclusivity or proximity arrangements, but the pricing premium over commodity chip markets can be substantial.
Energy operators—including biomass power plants, combined heat and power (CHP) installations, and district energy systems—form a third demand category. Several southeastern states maintain renewable portfolio standards that create utility-scale demand for wood fuel. Industrial facilities with high thermal loads, such as paper mills and food processors, are also evaluating on-site biomass combustion as a hedge against natural gas price volatility. This channel typically accepts a broader range of material quality but is highly sensitive to moisture content and delivered cost.
Where the Revenue Actually Disappears
Understanding why residue value goes uncaptured requires looking beyond the processing floor itself. The problem is rarely a single failure point. More often, it reflects a combination of organizational fragmentation, logistics blind spots, and market information gaps that compound one another.
At many mills, the individuals responsible for residue disposal—often operations or yard management personnel—have limited visibility into current buyer pricing or demand conditions. Residue is treated as a cost center to be minimized rather than a revenue stream to be optimized. Contract terms with local buyers, when they exist at all, may be years old and substantially below prevailing market rates. In some cases, mills pay tipping fees to dispose of material that buyers in adjacent markets would purchase at a positive price.
Logistics costs are a second major friction point. Wood residues are bulky, variable in moisture content, and expensive to transport relative to their value per ton. A buyer located 200 miles away may offer a nominally attractive price that evaporates entirely once freight is factored in. Without systematic freight modeling, mills cannot accurately evaluate which buyer relationships are genuinely profitable and which simply shift costs from disposal to transportation.
Organizational silos compound both problems. Sales teams focused on primary lumber and panel markets rarely have bandwidth or incentive to develop residue channels. Procurement relationships with buyers in the pellet or biochemical space require different commercial skills and longer development timelines than standard lumber sales. Without explicit ownership of residue revenue within the organizational structure, the opportunity tends to fall between functions.
Building the Infrastructure for Residue Revenue
Capturing residue value at scale is not a simple matter of making a few phone calls to regional buyers. It requires deliberate investment in three areas: market intelligence, logistics capability, and internal alignment.
On the market intelligence side, mills benefit from developing a clearer picture of the buyer landscape within their regional footprint. This means mapping pellet facilities, biochemical processors, and energy operators within a defined radius, understanding their current sourcing arrangements, and tracking the pricing indices relevant to each material type. Residue markets are less transparent than primary lumber markets, which creates both a challenge and an opportunity—operators who invest in market knowledge gain a negotiating advantage over those who accept whatever the spot buyer offers.
Logistics capability is the second investment area. For operations generating significant residue volumes, on-site preprocessing—screening, drying, or densification—can dramatically expand the range of accessible buyers and improve delivered economics. Pellet producers, for example, may pay meaningfully more for pre-dried sawdust than for green material, and the cost of on-site drying may be recoverable within a short operating period. Mills should conduct a frank cost-benefit analysis of preprocessing options before assuming that raw residue sales represent the ceiling of achievable value.
Internal alignment may be the most underappreciated lever. Assigning explicit revenue accountability for residue streams—whether through a dedicated business development role, a cross-functional team, or a formal residue sales function—signals organizational commitment and creates the conditions for sustained improvement. Some larger enterprises have found success by treating residue as a distinct product line with its own P&L visibility, which surfaces the true economics and incentivizes the kind of buyer development that rarely happens organically.
The Strategic Case for Acting Now
The biomass and wood residue market is not static. Regulatory tailwinds—including renewable energy incentives, carbon accounting requirements, and emerging clean fuel standards—are increasing buyer demand and, in some corridors, tightening supply. Mills that develop residue revenue relationships now are likely to secure better terms and longer commitments than those who enter the market after demand has fully matured.
There is also a competitive dimension. As more operations recognize the revenue potential of their residue streams, the negotiating leverage of any single seller diminishes. Early movers in a given region can establish preferred supplier relationships with buyers who have limited sourcing options—a position that becomes harder to replicate as the market develops.
For enterprise decision-makers evaluating where to direct operational improvement resources, the residue revenue gap deserves a prominent place in that conversation. The material is already being produced. The buyers exist. The infrastructure gaps, while real, are surmountable. What most US mills lack is not opportunity—it is the market intelligence and organizational will to convert that opportunity into revenue.